Key Takeaways
- Michael Burry is replacing short positions with put options on Micron, Nebius, SOXX and Palantir, aiming for cheaper leverage as he moves up his timeline for an AI bubble burst.
- His new puts point to next summer as a possible turning point for the AI trade, with longer-dated 2027 puts on SOXX and Palantir suggesting he’s watching more than one trigger.
- Burry cites an Ares Management report on shaky AI revenue assumptions and comments on returning chip-market cyclicality, even as the Nasdaq keeps hitting record highs.
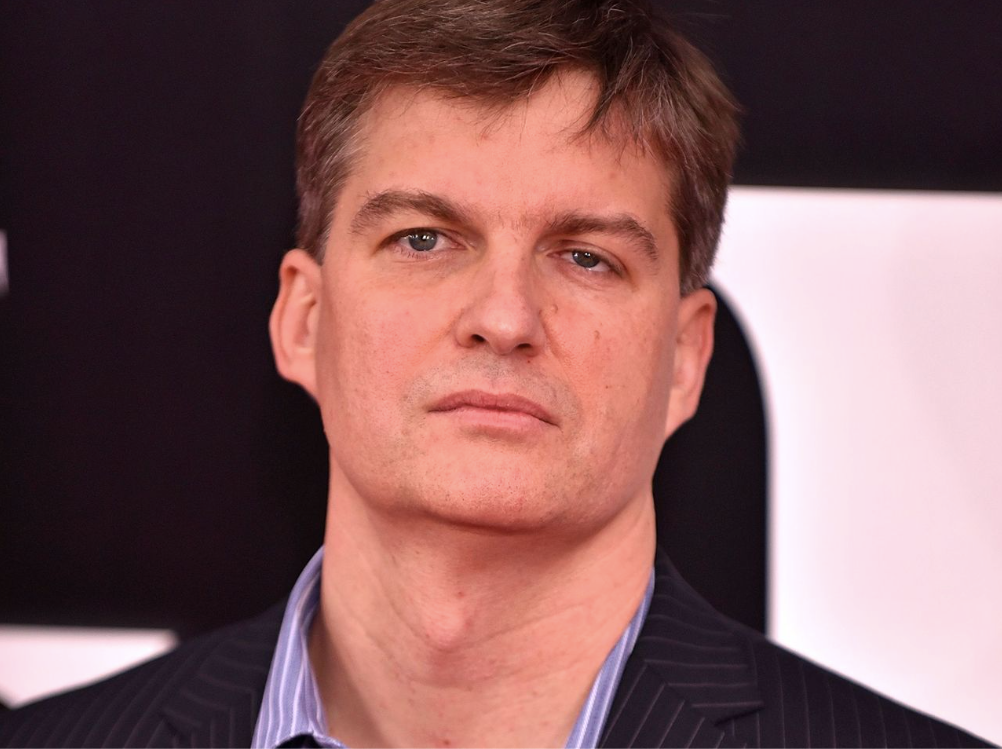
Michael Burry isn’t just staying bearish on AI. He’s speeding up the clock. The investor who famously shorted the housing market before the 2008 crash told subscribers this week that he’s moving his timeline forward, swapping short positions for put options to get more leverage over a shorter window.
Why Burry Is Switching to Puts
In his Monday newsletter, Burry explained the logic plainly: he wants more leverage, and cheap volatility is making that leverage attractive. With measures like the VIX unusually tight, put options have become a relatively inexpensive way to bet against a stock without the open-ended risk of a short position.
Some of the shift was about trimming his tax bill, Burry said. But the bigger driver is conviction. He thinks the AI bubble could burst sooner rather than later, and his new positions reflect that urgency. Several of his puts point to next summer as the moment when the AI trade could turn.
Also Read: Mistral CEO: AI Safety Warnings Are a “Cover” for Rivals’ Negligence
The New Positions, One by One
Burry rolled his Micron short into puts expiring in June with strikes around $500. His Nebius short became June puts in the “double digit strike price” range. His position against the SOXX semiconductor ETF shifted to September 2027 puts in the low $400s, and his Palantir short was replaced with an enlarged put position centered on a September 2027 expiration in the low $100s.
The structure matters here. Longer-dated, higher-conviction puts on some names paired with nearer-term June expirations on others suggest Burry sees more than one possible trigger point, not a single event he’s waiting on.
The Case Behind the Trade
Burry leaned on a recent Ares Management report warning about how much of the AI buildout rests on revenue that hasn’t materialized yet, backed by aggressive legal agreements. The report argues it would only take one disappointing season of AI revenue against heavy capital spending for company boards to shift their “highest-conviction bet” elsewhere, something the legal structures already anticipate.
He also pointed to comments from Acer CEO Jason Chen, who told Taiwanese media that memory chip cyclicality is set to return as Chinese production capacity keeps climbing. Chen’s argument undercuts the idea of a persistent shortage, since capacity gains should eventually pressure both supply and pricing.
A Long Wait for a Payoff That Hasn’t Come Yet
Burry has held this bearish stance for most of the year. Back in May, he compared the market to the final months of the 1999-2000 dot-com bubble. Since then, the Nasdaq Composite has kept climbing, closing at a record just last week, and Burry added to his shorts on Micron, Nebius and SOXX earlier this month.
Not every name has kept pace, though. Micron sits about 16% below its record high, and Palantir trades roughly 10% off its own peak. That gap between Burry’s thesis and the broader market’s momentum is exactly why he’s leaning into options now: leverage that pays off big if he’s right, without needing every stock to keep setting records for his bet to eventually work out.
Disclaimer: The information in this article is for general purposes only and does not constitute financial advice. The author’s views are personal and may not reflect the views of chainrant.com. Before making any investment decisions, you should always conduct your own research. chainrant.com is not responsible for any financial losses.